Does the same pension contribution cost the same take-home pay?
No. Salary sacrifice can reduce employee NI as well as Income Tax. Net pay normally gives Income Tax relief through payroll. Relief at source includes the provider’s basic-rate top-up here, but any extra relief claimed separately is excluded from take-home pay.
Scope and assumptions
- 2026/27 annual employee estimate, standard Personal Allowance with any income taper; employee NI category A, below State Pension age.
- No benefits in kind, tax-code adjustments, Child Benefit charge, other income or bonus. Pension and loan assumptions are stated in each table.
- Annual thresholds are used. Actual PAYE, NI and student-loan payroll deductions can differ because of pay-period thresholds, rounding and irregular pay.
- The gross contribution is 5% of the full original annual salary for every method. No student loans, employer contributions or employer NI sharing are included.
- Relief-at-source results are before additional separately claimed relief and are not a comparison of final settled tax liabilities. The provider’s basic-rate top-up is included in the gross pension amount.
- Salary sacrifice needs employer agreement and cannot reduce cash earnings below the applicable minimum wage. These examples leave at least £28,500 cash pay; hours and individual scheme limits must still be checked.
Calculated by the AfterTaxCalculator editorial team. This is a modelled comparison, not independently reviewed tax advice. Full methodology · Corrections
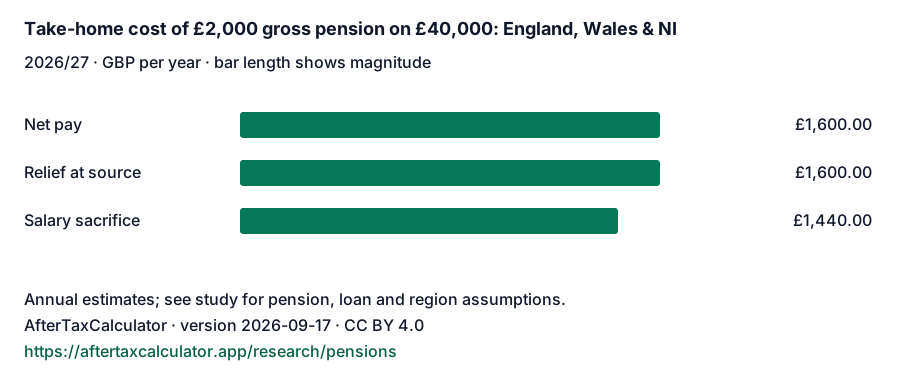
Take-home cost of £2,000 gross pension on £40,000: England, Wales & NI
GBP per year. Bar length shows magnitude; the signed value shows direction.
- Net pay£1,600.00
- Relief at source£1,600.00
- Salary sacrifice£1,440.00
Comparison data
30 scenarios. Monetary amounts are in GBP, rounded to two decimals after calculation. Each calculator link carries that row’s assumptions.
| Gross salary / year | Income Tax region | Method | Gross pension / year | Take-home cost / year | Take-home cost per £1 in pension | Adjust scenario |
|---|---|---|---|---|---|---|
| £30,000.00 | England, Wales & NI | Net pay | £1,500.00 | £1,200.00 | £0.80 | Calculate |
| £30,000.00 | England, Wales & NI | Relief at source | £1,500.00 | £1,200.00 | £0.80 | Calculate |
| £30,000.00 | England, Wales & NI | Salary sacrifice | £1,500.00 | £1,080.00 | £0.72 | Calculate |
| £40,000.00 | England, Wales & NI | Net pay | £2,000.00 | £1,600.00 | £0.80 | Calculate |
| £40,000.00 | England, Wales & NI | Relief at source | £2,000.00 | £1,600.00 | £0.80 | Calculate |
| £40,000.00 | England, Wales & NI | Salary sacrifice | £2,000.00 | £1,440.00 | £0.72 | Calculate |
| £60,000.00 | England, Wales & NI | Net pay | £3,000.00 | £1,800.00 | £0.60 | Calculate |
| £60,000.00 | England, Wales & NI | Relief at source | £3,000.00 | £2,400.00 | £0.80 | Calculate |
| £60,000.00 | England, Wales & NI | Salary sacrifice | £3,000.00 | £1,740.00 | £0.58 | Calculate |
| £100,000.00 | England, Wales & NI | Net pay | £5,000.00 | £3,000.00 | £0.60 | Calculate |
| £100,000.00 | England, Wales & NI | Relief at source | £5,000.00 | £4,000.00 | £0.80 | Calculate |
| £100,000.00 | England, Wales & NI | Salary sacrifice | £5,000.00 | £2,900.00 | £0.58 | Calculate |
| £110,000.00 | England, Wales & NI | Net pay | £5,500.00 | £2,200.00 | £0.40 | Calculate |
| £110,000.00 | England, Wales & NI | Relief at source | £5,500.00 | £3,300.00 | £0.60 | Calculate |
| £110,000.00 | England, Wales & NI | Salary sacrifice | £5,500.00 | £2,090.00 | £0.38 | Calculate |
| £30,000.00 | Scotland | Net pay | £1,500.00 | £1,195.26 | £0.80 | Calculate |
| £30,000.00 | Scotland | Relief at source | £1,500.00 | £1,200.00 | £0.80 | Calculate |
| £30,000.00 | Scotland | Salary sacrifice | £1,500.00 | £1,075.26 | £0.72 | Calculate |
| £40,000.00 | Scotland | Net pay | £2,000.00 | £1,580.00 | £0.79 | Calculate |
| £40,000.00 | Scotland | Relief at source | £2,000.00 | £1,600.00 | £0.80 | Calculate |
| £40,000.00 | Scotland | Salary sacrifice | £2,000.00 | £1,420.00 | £0.71 | Calculate |
| £60,000.00 | Scotland | Net pay | £3,000.00 | £1,740.00 | £0.58 | Calculate |
| £60,000.00 | Scotland | Relief at source | £3,000.00 | £2,400.00 | £0.80 | Calculate |
| £60,000.00 | Scotland | Salary sacrifice | £3,000.00 | £1,680.00 | £0.56 | Calculate |
| £100,000.00 | Scotland | Net pay | £5,000.00 | £2,750.00 | £0.55 | Calculate |
| £100,000.00 | Scotland | Relief at source | £5,000.00 | £4,000.00 | £0.80 | Calculate |
| £100,000.00 | Scotland | Salary sacrifice | £5,000.00 | £2,650.00 | £0.53 | Calculate |
| £110,000.00 | Scotland | Net pay | £5,500.00 | £1,787.50 | £0.33 | Calculate |
| £110,000.00 | Scotland | Relief at source | £5,500.00 | £3,162.50 | £0.58 | Calculate |
| £110,000.00 | Scotland | Salary sacrifice | £5,500.00 | £1,677.50 | £0.31 | Calculate |
Download and cite
Download CSV · Download JSON with assumptions and sources · Download chart
Suggested citation: AfterTaxCalculator editorial team, “Pension methods: compare the cost to take-home pay”, 2026/27 tax year, version 2026-09-17, https://aftertaxcalculator.app/research/pensions.
The original data and chart are licensed under Creative Commons Attribution 4.0. Credit AfterTaxCalculator, link to this page, retain the tax year and assumptions, and identify any changes. This licence does not cover material on external source websites. Dated downloads remain available when a later version is published.
Official sources
- HMRC employer rates and thresholds 2026/27
- Scottish Government rates and bands 2026/27
- HMRC salary sacrifice guidance
- HMRC pension tax relief and claims
Publication date identifies this comparison’s version; the calculator’s underlying rate verification dates are recorded in the methodology.