Why can the same pay rise produce different take-home pay?
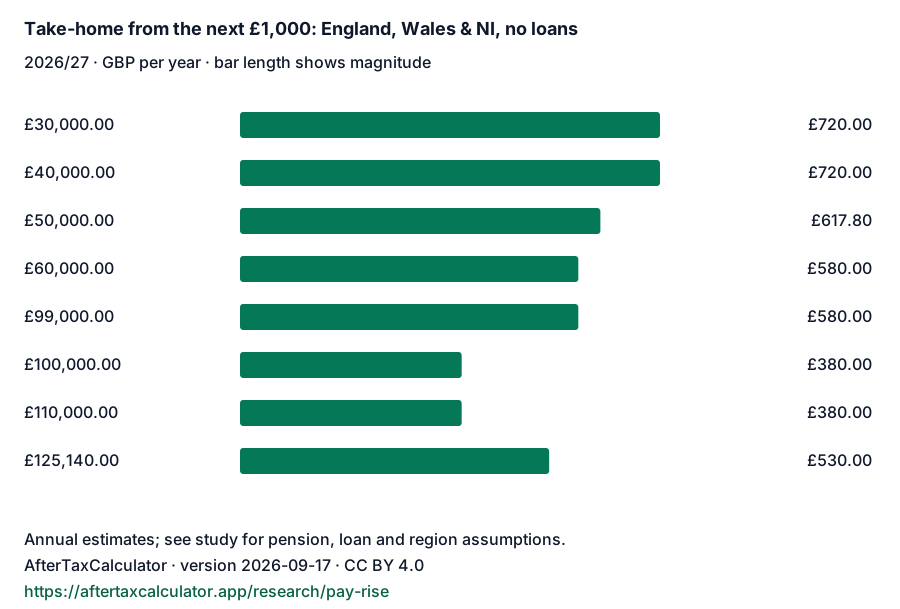
With no pension or loans in England, Wales or Northern Ireland, a rise from £40,000 to £41,000 adds £720.00 to annual take-home pay. From £100,000 to £101,000 it adds £380.00, because the Personal Allowance starts to taper.
Scope and assumptions
- 2026/27 annual employee estimate, standard Personal Allowance with any income taper; employee NI category A, below State Pension age.
- No benefits in kind, tax-code adjustments, Child Benefit charge, other income or bonus. Pension and loan assumptions are stated in each table.
- Annual thresholds are used. Actual PAYE, NI and student-loan payroll deductions can differ because of pay-period thresholds, rounding and irregular pay.
- No pension. Each row adds £1,000 of recurring gross annual salary; monthly gain is the annual difference divided by 12. This is an increment comparison, not the rate on the whole salary.
Calculated by the AfterTaxCalculator editorial team. This is a modelled comparison, not independently reviewed tax advice. Full methodology · Corrections
Take-home from the next £1,000: England, Wales & NI, no loans
GBP per year. Bar length shows magnitude; the signed value shows direction.
- £30,000.00£720.00
- £40,000.00£720.00
- £50,000.00£617.80
- £60,000.00£580.00
- £99,000.00£580.00
- £100,000.00£380.00
- £110,000.00£380.00
- £125,140.00£530.00
Comparison data
32 scenarios. Monetary amounts are in GBP, rounded to two decimals after calculation. Each calculator link carries that row’s assumptions.
| Gross salary / year | Income Tax region | Loan deductions | Extra take-home / year | Extra take-home / month | Share of rise kept | Adjust scenario |
|---|---|---|---|---|---|---|
| £30,000.00 | England, Wales & NI | None | £720.00 | £60.00 | 72% | Calculate |
| £40,000.00 | England, Wales & NI | None | £720.00 | £60.00 | 72% | Calculate |
| £50,000.00 | England, Wales & NI | None | £617.80 | £51.48 | 61.78% | Calculate |
| £60,000.00 | England, Wales & NI | None | £580.00 | £48.33 | 58% | Calculate |
| £99,000.00 | England, Wales & NI | None | £580.00 | £48.33 | 58% | Calculate |
| £100,000.00 | England, Wales & NI | None | £380.00 | £31.67 | 38% | Calculate |
| £110,000.00 | England, Wales & NI | None | £380.00 | £31.67 | 38% | Calculate |
| £125,140.00 | England, Wales & NI | None | £530.00 | £44.17 | 53% | Calculate |
| £30,000.00 | England, Wales & NI | Plan 2 + postgraduate | £570.00 | £47.50 | 57% | Calculate |
| £40,000.00 | England, Wales & NI | Plan 2 + postgraduate | £570.00 | £47.50 | 57% | Calculate |
| £50,000.00 | England, Wales & NI | Plan 2 + postgraduate | £467.80 | £38.98 | 46.78% | Calculate |
| £60,000.00 | England, Wales & NI | Plan 2 + postgraduate | £430.00 | £35.83 | 43% | Calculate |
| £99,000.00 | England, Wales & NI | Plan 2 + postgraduate | £430.00 | £35.83 | 43% | Calculate |
| £100,000.00 | England, Wales & NI | Plan 2 + postgraduate | £230.00 | £19.17 | 23% | Calculate |
| £110,000.00 | England, Wales & NI | Plan 2 + postgraduate | £230.00 | £19.17 | 23% | Calculate |
| £125,140.00 | England, Wales & NI | Plan 2 + postgraduate | £380.00 | £31.67 | 38% | Calculate |
| £30,000.00 | Scotland | None | £710.00 | £59.17 | 71% | Calculate |
| £40,000.00 | Scotland | None | £710.00 | £59.17 | 71% | Calculate |
| £50,000.00 | Scotland | None | £543.80 | £45.32 | 54.38% | Calculate |
| £60,000.00 | Scotland | None | £560.00 | £46.67 | 56% | Calculate |
| £99,000.00 | Scotland | None | £530.00 | £44.17 | 53% | Calculate |
| £100,000.00 | Scotland | None | £305.00 | £25.42 | 30.5% | Calculate |
| £110,000.00 | Scotland | None | £305.00 | £25.42 | 30.5% | Calculate |
| £125,140.00 | Scotland | None | £500.00 | £41.67 | 50% | Calculate |
| £30,000.00 | Scotland | Plan 2 + postgraduate | £560.00 | £46.67 | 56% | Calculate |
| £40,000.00 | Scotland | Plan 2 + postgraduate | £560.00 | £46.67 | 56% | Calculate |
| £50,000.00 | Scotland | Plan 2 + postgraduate | £393.80 | £32.82 | 39.38% | Calculate |
| £60,000.00 | Scotland | Plan 2 + postgraduate | £410.00 | £34.17 | 41% | Calculate |
| £99,000.00 | Scotland | Plan 2 + postgraduate | £380.00 | £31.67 | 38% | Calculate |
| £100,000.00 | Scotland | Plan 2 + postgraduate | £155.00 | £12.92 | 15.5% | Calculate |
| £110,000.00 | Scotland | Plan 2 + postgraduate | £155.00 | £12.92 | 15.5% | Calculate |
| £125,140.00 | Scotland | Plan 2 + postgraduate | £350.00 | £29.17 | 35% | Calculate |
Download and cite
Download CSV · Download JSON with assumptions and sources · Download chart
Suggested citation: AfterTaxCalculator editorial team, “How much of a £1,000 pay rise do you keep?”, 2026/27 tax year, version 2026-09-17, https://aftertaxcalculator.app/research/pay-rise.
The original data and chart are licensed under Creative Commons Attribution 4.0. Credit AfterTaxCalculator, link to this page, retain the tax year and assumptions, and identify any changes. This licence does not cover material on external source websites. Dated downloads remain available when a later version is published.
Official sources
- HMRC employer rates and thresholds 2026/27
- Scottish Government rates and bands 2026/27
- HMRC student-loan payroll guidance
Publication date identifies this comparison’s version; the calculator’s underlying rate verification dates are recorded in the methodology.